HSA as a Retirement Account: The Triple-Tax Advantage
Learn how to use a Health Savings Account (HSA) as a powerful retirement investment tool with tax-deductible contributions and tax-free compounding.
Retirement planning discussions almost universally focus on workplace 401(k) plans and individual retirement accounts. Savers construct asset allocation models, analyze fund expense ratios, and project compound growth across these standard accounts.
Yet millions of investors overlook an extraordinary tax shelter hiding directly inside their annual employer benefits package. The Health Savings Account (HSA) delivers mathematical tax advantages that exceed both traditional and Roth retirement structures.
Key Takeaways
- The HSA is the only account in the federal tax code offering a complete triple-tax advantage.
- Paying current medical expenses out of pocket allows invested HSA balances to compound undisturbed for decades.
- The IRS establishes no time limit on reimbursing past qualified medical expenses with saved receipts.
- After age 65, HSA funds can be withdrawn for non-medical expenses subject only to ordinary income tax, exactly like a traditional 401(k).
The Spending Myth: Why Most Savers Misuse Their Health Savings Account
Most employees treat an HSA as an annual medical spending reservoir, confusing it with a “use-it-or-lose-it” Flexible Spending Account (FSA). They deposit pre-tax dollars, incur a routine prescription charge, and immediately swipe their account debit card.
According to research published by the Employee Benefit Research Institute, fewer than 15% of HSA account holders invest their funds in market securities. The vast majority leave their balances sitting in low-yield cash accounts, forfeiting decades of compound capital growth.
Incorporating healthcare outlays into retirement planning basics and healthcare projections reveals a sobering reality. Long-term expenditure surveys from the Bureau of Labor Statistics Consumer Expenditure Survey indicate that healthcare represents one of the largest and fastest-growing expense categories for older Americans.
A 65-year-old retiring today requires an estimated $165,000 or more in dedicated savings exclusively for post-work healthcare premiums, co-pays, and deductibles. Deploying an HSA as a long-term investment vehicle creates a targeted, tax-free fund to neutralize this substantial expense.
The Triple-Tax Advantage: How the HSA Outperforms 401(k) and Roth Accounts
The unique financial power of the Health Savings Account stems from its statutory triple-tax shelter, authorized under Internal Revenue Code Section 223:
HSA Future Value = Initial Deposit × (1 + r)^n + Annual Contribution × [((1 + r)^n - 1) ÷ r]
Annual Tax Shield = Contribution × (Marginal Income Tax Rate + 7.65% FICA Exemption)
First, contributions made through employer payroll cafeteria plans are 100% exempt from federal income taxes, state income taxes (in 48 states), and mandatory 7.65% FICA payroll taxes. Direct contributions made with personal post-tax funds qualify as an above-the-line deduction on Form 1040 Schedule 1.
Second, dividends, capital gains, and interest generated inside the account compound completely free of annual taxation.
Third, withdrawals utilized for qualified medical expenses are permanently exempt from federal and state income taxes. A traditional 401(k) taxes withdrawals as ordinary income upon distribution, while a Roth IRA requires after-tax contribution dollars. The HSA avoids taxation at contribution, during accumulation, and upon distribution.
Placing the HSA at the proper stage within the financial order of operations allows savers to capture this compounding advantage right alongside their workplace employer match.
Under IRS Revenue Procedure 2025-19, the statutory contribution limit for the 2026 tax year is $4,400 for self-only coverage and $8,750 for family coverage. Account owners aged 55 and older can contribute an additional $1,000 catch-up deposit annually.
Compare Healthcare & Investment Scenarios: Analyze whether an HDHP saves more total dollars than a traditional plan with our HDHP vs. PPO Calculator, or model your multi-decade compound balance in our HSA Calculator.
At-A-Glance: Comparing HSA, Traditional 401(k), and Roth IRA
The following comparison contrasts the tax mechanics, investment freedoms, and distribution rules across the three primary retirement accounts:
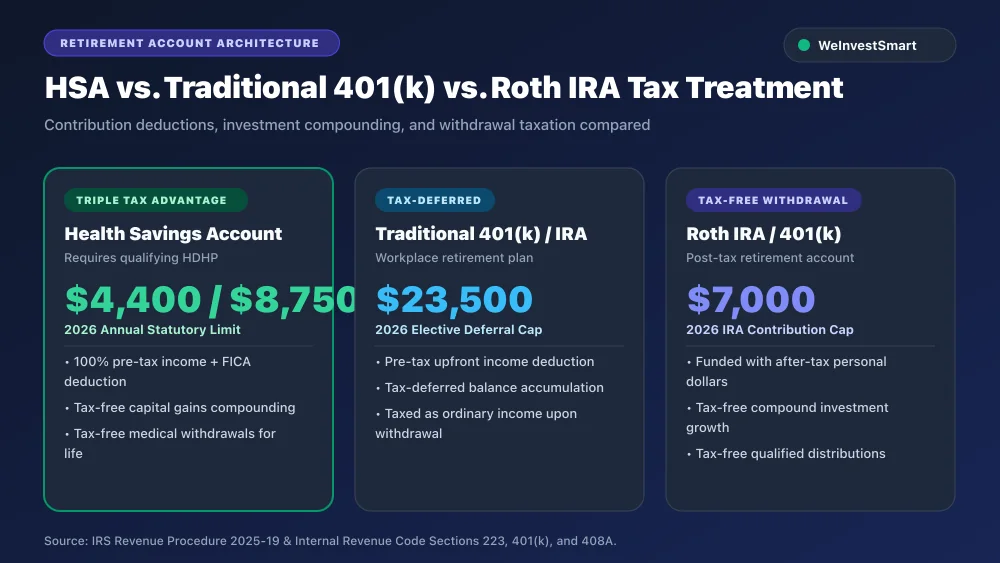
| Account Feature | Health Savings Account (HSA) | Traditional 401(k) | Roth IRA |
|---|---|---|---|
| Upfront Contribution Tax Break | Yes (Federal, State, and FICA) | Yes (Federal and State) | No (Post-Tax Dollars) |
| Tax-Free Investment Compounding | Yes (Zero capital gains tax) | Yes (Tax-Deferred) | Yes (100% Tax-Free) |
| Tax-Free Qualified Distributions | Yes (For medical expenses) | No (Taxed as Ordinary Income) | Yes (For qualified withdrawals) |
| 2026 Contribution Limit (Single) | $4,400 ($1,000 catch-up at 55+) | $23,500 ($7,500 catch-up at 50+) | $7,000 ($1,000 catch-up at 50+) |
| Required Minimum Distributions | None | Yes (Starting at Age 73 to 75) | None |
| Post-Age-65 Flexibility | Penalty-free for any use | Ordinary income tax on all draws | Tax-free withdrawals |
The ‘Stealth IRA’ Strategy: Investing and Shoe-Boxing Medical Receipts
Maximizing an HSA requires treating it as a long-term retirement investment vehicle rather than a transaction account. The core strategy requires paying current minor medical bills with everyday cash flow while leaving your invested balance untouched.
Under IRS Publication 969 on Health Savings Accounts, there is no statutory time limit governing when an account holder must claim reimbursement for an out-of-pocket expense. A qualifying medical cost incurred at age 35 can be reimbursed at age 65 or 70.
This rule enables the “shoe-box strategy.” Savers digitize and preserve receipts for every doctor co-pay, prescription, dental procedure, and optical purchase across their working careers.
While your receipts sit archived in cloud storage, the corresponding dollars remain invested in broad equities, compounding tax-free over several decades. Late-career savers implementing aggressive catch-up retirement strategies can use this method to build a massive pool of future tax-free liquidity.
Upon entering retirement, you can withdraw thousands of dollars tax-free from your HSA as lump-sum reimbursements for those historical expenses, utilizing the money for any purpose without penalty.
Qualified Medical Expenses: Expanding the Scope of Tax-Free Withdrawals
Understanding what constitutes an eligible medical expense under Internal Revenue Code Section 213(d) maximizes the long-term utility of your accumulated balance. The statutory definition extends far beyond emergency hospital procedures and routine physician appointments.
Eligible outpatient healthcare expenses include:
- Prescription medications, insulin, diagnostic test kits, and specialized medical monitoring equipment.
- Dental cleanings, orthodontic braces, periodontal surgery, root canals, and restorative crowns.
- Eye exams, prescription eyeglasses, contact lenses, contact solution, and corrective laser eye surgery.
- Mental health counseling, psychiatric evaluations, substance abuse treatments, and physical therapy sessions.
- Over-the-counter allergy medications, pain relievers, cold remedies, and feminine care products permanently authorized under federal legislation.
During retirement, HSA dollars can also be applied toward qualified long-term care insurance premiums up to age-based statutory limits. Under IRS revenue procedures, taxpayers age 60 to 70 can deduct up to $4,710 in annual premiums, while individuals over age 70 can apply up to $5,880 tax-free from their HSA. This tax-deductible reimbursement shields other retirement assets from being eroded by nursing home costs.
Furthermore, post-65 retirees can use HSA funds tax-free to cover Medicare Part B, Part D, and Medicare Advantage premiums, as well as Medicare co-payments and deductibles.
Estate Planning: Spousal Transfer vs. The Non-Spouse Tax Trap
Estate planning represents an essential component of long-term HSA strategy that many account owners overlook. How an HSA is treated after your death depends entirely on who you designate as your primary beneficiary.
The Spousal Transfer Advantage
If your legally married spouse is designated as the primary beneficiary, the transfer is seamless. Under Internal Revenue Code Section 223(f)(8), the HSA automatically becomes the property of your surviving spouse upon your death. The surviving spouse assumes full ownership, retains the account’s tax-exempt status, and enjoys continued tax-free compounding and medical reimbursements without incurring immediate income taxes.
The Non-Spouse Inheritance Tax Trap
If you name a non-spouse beneficiary, such as an adult child, sibling, or family trust, the account loses its HSA status immediately on the date of your death. The entire fair market value of the account becomes taxable ordinary income to that non-spouse beneficiary in the year of death.
For example, if an adult child inherits a $250,000 HSA, that entire $250,000 is added to their gross taxable income in a single year, potentially pushing them into the top 37% federal tax bracket. To avoid this severe tax drag, financial planners recommend naming your spouse as primary beneficiary, or strategically spending down invested HSA balances on medical needs during your lifetime while leaving Roth IRAs or taxable brokerage assets (which receive a stepped-up cost basis) to non-spouse heirs.
Case Study: How Jordan Accumulated $406,000 for Retirement Inside an HSA
Jordan, a 35-year-old engineering project manager earning $105,000 annually, enrolled in an employer-sponsored High-Deductible Health Plan with full HSA eligibility.
Rather than spending his contributions on annual dental cleanings and prescriptions, Jordan automated a monthly contribution to max out the statutory annual limit. He established an emergency fund using an interactive emergency fund calculator to guarantee he could cover out-of-pocket deductibles without touching his invested HSA.
Jordan invested 100% of his HSA deposits into a low-cost total U.S. stock market index fund yielding a 7% average annualized real return. Simultaneously, he archived $1,600 per year in routine medical receipts in a digital folder.
Over a 30-year career from age 35 to 65, Jordan’s cumulative contributions totaled $129,000. Through the compounding engine of tax-free growth, his invested HSA balance reached approximately $406,000 at age 65.
Furthermore, Jordan held $48,000 in documented medical receipts. At age 65, he withdrew $48,000 completely tax-free to remodel his home, leaving more than $358,000 invested to cover all remaining healthcare needs throughout his retirement years.
HSA Rules After Age 65: Medicare Coordination and Penalty-Free Withdrawals
Reaching age 65 introduces substantial structural changes to HSA management that enhance your financial flexibility:
- Elimination of Non-Medical Penalties: The standard 20% excise penalty on non-medical distributions disappears completely at age 65. If you withdraw HSA funds to travel or pay household bills, you pay only ordinary income tax, identical to distributions from a traditional 401(k) or IRA.
- Medicare Premium Payments: HSA funds can be used tax-free to pay premiums for Medicare Part B, Medicare Part D, and Medicare Advantage plans. However, HSA dollars cannot be used to pay for Medigap supplemental policy premiums.
- Contribution Cessation Upon Medicare Enrollment: Once you enroll in Medicare Part A or Part B, you must cease all further contributions to an HSA. IRS regulations include a six-month retroactive coverage window, meaning savers should halt HSA contributions six months prior to applying for Medicare benefits.
Maintaining a substantial HSA balance into your late sixties protects traditional taxable retirement assets from being liquidated to satisfy steep medical deductibles.
State Tax Caveats: California and New Jersey Tax Treatment
While the federal government and 48 states grant full tax deductions and tax-free growth for HSAs, California and New Jersey do not conform to federal HSA tax legislation.
Residents in California and New Jersey face specific state tax rules:
- Contributions to an HSA are not deductible on state income tax returns.
- Interest, dividends, and capital gains generated inside an HSA are subject to annual state income taxation.
- Taxpayers in these states must track their cost basis in HSA investments to calculate state capital gains when securities are sold.
Despite this state-level limitation, the federal tax savings and FICA payroll tax exemptions remain so substantial that maximizing an HSA remains mathematically advantageous even for residents of California and New Jersey. Filers looking to lower their overall liabilities should also review strategies to lower taxable income across federal schedules.
Step-by-Step Implementation: Maximizing Your HSA Investment Portfolio
Executing an institutional-grade HSA strategy requires selecting the right provider and following a disciplined workflow:
- Verify HDHP Statutory Qualification: Confirm your health plan meets IRS annual requirements for minimum deductibles ($1,700 self-only / $3,400 family in 2026) and maximum out-of-pocket limits ($8,300 self-only / $16,600 family).
- Select an Investment-Friendly Custodian: If your employer-selected custodian charges excessive monthly maintenance fees or lacks low-cost index options, open an individual HSA with a zero-fee independent brokerage.
- Automate Payroll Deferrals: Set automated payroll deductions to capture FICA tax exemptions (saving 7.65%) in addition to federal and state tax write-offs.
- Deploy Assets into Low-Cost Index Funds: Transition balances exceeding your immediate insurance deductible into low-cost index fund investing across broad equities.
- Establish Digital Receipt Archiving: Store itemized hospital bills, pharmacy receipts, and explanation-of-benefits statements in secure cloud storage.
Frequently Asked Questions About Using an HSA for Retirement
Why is an HSA considered a powerful retirement account?
A Health Savings Account provides an unmatched triple-tax advantage that combines pre-tax salary contributions, tax-free investment growth, and tax-free withdrawals for qualified medical expenses. No other retirement vehicle in the United States tax code offers complete tax exemption across all three stages.
What is the HSA receipt shoe-boxing strategy?
The shoe-boxing strategy involves paying current out-of-pocket medical bills with personal cash while archiving digital receipts indefinitely. Because the IRS imposes no deadline on reimbursements, account owners can allow their invested balances to compound for decades before withdrawing tax-free cash in retirement.
What are the 2026 HSA contribution limits and eligibility requirements?
For the 2026 tax year, individuals can contribute up to $4,400, while families can contribute up to $8,750, with an additional $1,000 catch-up allowance for savers aged 55 and older. Eligibility requires enrollment in a qualifying High-Deductible Health Plan with minimum statutory deductibles.
What happens to your HSA funds after reaching age 65?
After reaching age 65, the 20% non-medical withdrawal penalty disappears, allowing account owners to withdraw funds for general living expenses subject only to ordinary income tax. Qualified healthcare withdrawals remain completely tax-free for life, functioning as a flexible retirement cushion.
Can you invest HSA balances in index funds and stocks?
Yes, top HSA custodians allow account holders to allocate funds beyond a basic cash threshold into broad stock market index funds and exchange-traded funds. Investing balances across diversified equities ensures your healthcare savings outpace medical price inflation over multi-decade horizons.
This article is for educational purposes only and should not be considered personalized financial advice. Consider consulting with a certified financial planner (CFP) or tax advisor for guidance specific to your situation.
For educational purposes. Consider your own circumstances before making financial decisions. Read our editorial policy.
From reading to planning
Explore the numbers for yourself.
Use our free calculators to compare scenarios and understand your options.