How Much Do You Actually Need to Retire? The 4% Rule Explained
Calculate how much money you need to retire using the 4% rule and the Rule of 25, sequence of returns risk, and dynamic guardrail withdrawal strategies.
Most retirement advice is filled with vague platitudes: save early and often, invest for the long term, and live below your means. While that advice is well-intentioned, it leaves out the single most important number an aspiring retiree needs: a concrete, mathematical portfolio target.
Key Takeaways
- The 4% Rule Baseline: You withdraw 4% of your starting nest egg in Year 1 and adjust subsequent annual distributions for inflation over a 30-year horizon.
- The Rule of 25: Multiply your estimated annual retirement living expenses by 25 to establish your baseline Financial Independence (FI) portfolio number.
- Sequence of Returns Risk: Severe market declines during your first five years of retirement pose the greatest threat to long-term portfolio survival.
- Dynamic Guardrails: Incorporating flexible withdrawal rules allows retirees to safely start at higher withdrawal rates (4.5% to 5.0%) by trimming spending during bear markets.
Understanding the historical foundation and mathematical limits of safe withdrawal rates allows you to replace anxiety with a structured, testable retirement roadmap.
Understanding Your Retirement Number: How the 4% Rule Operates
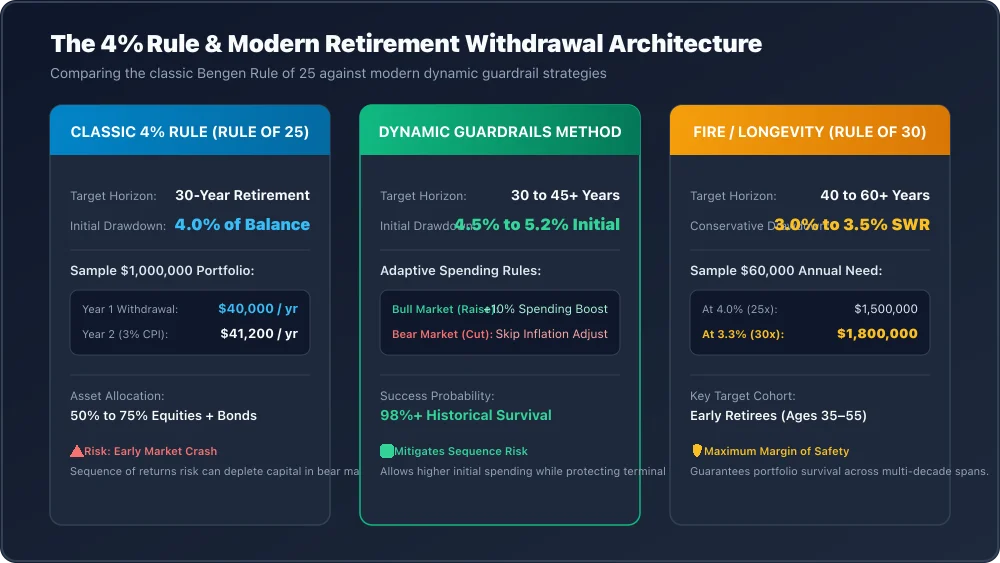
The 4% rule is an empirical guideline originating from financial planning research in the 1990s. It dictates that an investor with a balanced stock-and-bond portfolio can safely withdraw 4% of their total accumulated assets in their first year of retirement. In each subsequent year, the retiree adjusts that dollar withdrawal amount by the prevailing rate of inflation, regardless of market volatility.
According to research documented in the landmark Trinity Study published in the AAII Journal, this method achieved a 95% to 98% historical success rate across rolling 30-year market cycles between 1926 and 1995.
Let us trace how the math functions over your first three years of retirement:
- Starting Portfolio: Imagine you retire with an accumulated nest egg of $1,000,000.
- Year 1 Distribution: You withdraw exactly 4% of your starting capital: $40,000 ($1,000,000 × 0.04).
- Year 2 Distribution: If the Consumer Price Index (CPI) increases by 3.0%, you adjust your initial $40,000 by 3.0%: $41,200 ($40,000 × 1.03).
- Year 3 Distribution: If inflation rises by an additional 2.5%, you multiply $41,200 by 1.025: $42,230.
Notice that the 4% calculation occurs only once, on the day you officially retire. After Year 1, your annual withdrawal amount is decoupled from your day-to-day portfolio balance and tracks inflation to preserve your real standard of living.
Initial Annual Withdrawal = Starting Retirement Portfolio × Safe Withdrawal Rate (4.0%)
Establishes your baseline purchasing power for the first twelve months of retirement.
Year n Withdrawal = Year (n - 1) Withdrawal × (1 + Annual Inflation Rate)
Maintains constant inflation-adjusted purchasing power across subsequent retirement years.
The Rule of 25: Calculating Your Financial Independence Target
The greatest practical benefit of the 4% rule is its mathematical inverse, widely known as the Rule of 25. If you withdraw 4% of your capital each year, you need a portfolio equal to 25 times your annual living expenses (since 1 ÷ 0.04 = 25).
Target Retirement Portfolio = Annual Retirement Expenses × 25
Calculates total invested capital required to support a 4.0% perpetual safe withdrawal rate.
By tabulating your anticipated post-retirement living expenses, you can immediately solve for your savings target:
- Modest Lifestyle ($40,000 Annual Need): $40,000 × 25 = $1,000,000
- Comfortable Lifestyle ($60,000 Annual Need): $60,000 × 25 = $1,500,000
- Affluent Lifestyle ($100,000 Annual Need): $100,000 × 25 = $2,500,000
- Executive Lifestyle ($150,000 Annual Need): $150,000 × 25 = $3,750,000
To determine realistic household expenditure baselines, cross-reference your spending with published data from the Bureau of Labor Statistics Consumer Expenditure Surveys. For comprehensive tax-reduction strategies to speed up your accumulation phase, review our guides on how to lower taxable income and marginal vs effective tax rates.
Model Your Financial Independence Timeline Calculate your exact savings runway, target portfolio number, and safe withdrawal horizon using our interactive FIRE Financial Independence Calculator. To test how long an existing portfolio survives varying monthly withdrawals, explore our Savings Withdrawal Calculator.
Where Did the 4% Rule Come From? Bengen and the Trinity Study
The 4% rule was not created by marketing departments; it emerged from empirical academic stress-testing of historical market returns.
In 1994, MIT-trained aeronautical engineer turned certified financial planner William Bengen published a groundbreaking paper in the Journal of Financial Planning. Bengen sought to determine the maximum sustainable withdrawal rate (which he coined “SAFEMAX”) that would survive every historical 30-year economic catastrophe in modern American history.
Bengen modeled historical asset returns starting in 1926, deliberately exposing portfolios to:
- The Great Depression of 1929 and the subsequent 86% market collapse.
- The severe stagflation of 1973 to 1974, which paired double-digit inflation with a 48% real market drawdown.
- Prolonged bond bear markets during the mid-20th century.
Bengen discovered that for any portfolio allocated between 50% and 75% in large-cap equities (S&P 500) and the remainder in intermediate-term government bonds, a 4.0% initial withdrawal adjusted for inflation never exhausted capital in less than 33 years. In 80% of historical periods, the portfolio ended Year 30 with more than its original purchasing power.
In 1998, professors Philip L. Cooley, Louis E. Carlsen, and Charles M. Hubbard of Trinity University replicated and expanded Bengen’s work across thousands of rolling periods, establishing the Trinity Study as a foundational pillar of modern financial independence planning.
The Flaws and Risks of Relying Solely on the 4% Rule
While the 4% rule provides an exceptional rule of thumb, applying it blindly to a 21st-century retirement introduces significant financial risks.
1. Sequence of Returns Risk
Sequence of returns risk represents the single greatest mathematical hazard facing new retirees. This risk refers to the order in which investment returns occur. Experiencing severe bear markets during your first five years of retirement can permanently impair your portfolio, even if multi-decade average returns appear robust.
Consider two hypothetical retirees, both starting with $1,000,000 portfolios and withdrawing $40,000 annually adjusted for inflation:
- Retiree A (Favorable Sequence): Experiences a 15% market rally in Year 1 and an 18% rally in Year 2. Their portfolio expands to $1,250,000 despite distributions. When a bear market strikes in Year 8, their capital cushion absorbs the blow comfortably.
- Retiree B (Unfavorable Sequence): Retires on the eve of a recession and suffers back-to-back 20% market declines in Years 1 and 2. Their portfolio shrinks from $1,000,000 to approximately $600,000 while they are forced to liquidate shares at depressed valuations to cover living expenses. Even if markets rally vigorously in Year 4, the reduced share count cannot generate enough compounding to recover, leading to premature capital exhaustion.
2. Longevity Risk and the FIRE Movement
William Bengen and the authors of the Trinity Study designed the 4% rule specifically for a 30-year retirement horizon (retiring at age 65 and planning through age 95). According to the Social Security Administration Period Life Table, a married couple retiring at 65 has a 50% probability of at least one spouse reaching age 92.
However, participants in the Financial Independence, Retire Early (FIRE) movement frequently retire in their thirties, forties, or early fifties. For an early retiree facing a 45 to 60-year retirement horizon, a static 4.0% withdrawal rate carries a failure probability exceeding 18% over historical periods.
To achieve 100% historical survival over 50-year spans, early retirees frequently adopt the Rule of 30 (a 3.33% safe withdrawal rate) or the Rule of 33 (a 3.0% safe withdrawal rate).
| Withdrawal Rate | Portfolio Multiple (Inverse) | Target for $60k Expenses | Target for $80k Expenses | Safe Horizon |
|---|---|---|---|---|
| 4.00% (Rule of 25) | 25.0x Annual Expenses | $1,500,000 | $2,000,000 | 30 Years |
| 3.50% (Rule of 28.5) | 28.6x Annual Expenses | $1,714,000 | $2,286,000 | 40 Years |
| 3.25% (Rule of 30.7) | 30.8x Annual Expenses | $1,846,000 | $2,462,000 | 50+ Years |
| 3.00% (Rule of 33.3) | 33.3x Annual Expenses | $2,000,000 | $2,667,000 | Perpetual Endowments |
Target Multiple = 100 ÷ Chosen Safe Withdrawal Rate (%)
Calculates the required wealth multiple based on your personal retirement duration and risk tolerance.
3. Rigid Behavioral Assumptions
The 4% rule assumes that retirees act like automated software, increasing their spending mechanically each year regardless of economic conditions. In the real world, retirees exhibit natural spending elasticity: they travel and dine out less during major recessions, postpone automotive replacements, and naturally trim consumption as they transition from active early retirement into later decades.
Modern Adaptive Withdrawal Strategies
To eliminate the rigidity of the 4% rule, modern financial planners implement dynamic withdrawal frameworks that adjust to real-world market movements.
1. The Guyton-Klinger Guardrails Method
The Guyton-Klinger guardrails method provides a dynamic alternative to static spending rules. Instead of adjusting withdrawals solely by inflation, you establish upper and lower performance boundaries:
- Capital Preservation Rule: If your current withdrawal rate rises more than 20% above your initial rate (due to a market decline), you reduce your spending distribution by 10% to protect principal.
- Prosperity Rule: If your current withdrawal rate falls more than 20% below your initial rate (due to substantial portfolio growth), you give yourself a 10% permanent spending raise.
Because guardrails dynamically defend portfolio principal during bear markets, retirees can safely adopt a higher initial withdrawal rate of 4.5% to 5.2% without increasing terminal ruin risk.
2. The Three-Bucket Cash Management Strategy
The Three-Bucket strategy segments your retirement assets across distinct time horizons to insulate day-to-day spending from equity volatility:
- Bucket 1 (Immediate Cash: 1 to 2 Years): Stored in high-yield savings, money market funds, and short-term Treasury bills. All monthly living expenses are drawn directly from this liquid bucket.
- Bucket 2 (Bridge Income: 3 to 7 Years): Invested in high-quality short-to-intermediate corporate and government bonds, dividend-paying equities, and certificates of deposit (CDs).
- Bucket 3 (Long-Term Growth: 8+ Years): Invested fully in diversified equity index funds. When equities enter a bear market, you pause distributions from Bucket 3 and live off Buckets 1 and 2, allowing growth assets to recover without forced liquidations.
Structuring retirement accounts across pre-tax, Roth, and taxable vehicles also optimizes tax efficiency. For account structuring strategies, explore our detailed comparisons of SEP IRA vs Solo 401(k) and HSA retirement advantages.
How Social Security and Pensions Reduce Your Required Nest Egg
A frequent mistake in retirement planning is calculating your Rule of 25 target using your total spending budget rather than your net portfolio deficit. Guaranteed income sources directly reduce the capital your portfolio must support.
Net Annual Portfolio Need = Total Living Expenses - (Social Security + Guaranteed Pensions)
Isolates the exact annual cash flow burden that your invested savings must generate.
Consider David and Elena, who anticipate annual living expenses of $80,000 in retirement:
- Without Social Security: An annual living expense of $80,000 multiplied by 25 requires a baseline nest egg of $2,000,000
- With Combined Social Security of $35,000/year: Their net portfolio need drops to $45,000 ($80,000 minus $35,000)
- Adjusted Target Nest Egg: An annual deficit of $45,000 multiplied by 25 produces an adjusted target of $1,125,000
Factoring in Social Security benefits reduced David and Elena’s required portfolio target by $875,000 (a 43.7% reduction in necessary savings).
Practical Steps to Implement Your Retirement Plan
- Calculate Baseline Annual Expenses: Track your actual household outlays over the past twelve months, subtracting mortgage payments or child-related expenses that will sunset prior to retirement.
- Subtract Guaranteed Income Streams: Deduct projected Social Security benefits, military pensions, or rental property cash flow to find your net annual portfolio deficit.
- Select Your Safe Withdrawal Rate: Use 4.0% (25x) for a standard 30-year retirement, or 3.25% to 3.50% (28x to 31x) for early retirement horizons exceeding 35 years.
- Deploy Dynamic Guardrails: Establish spending rules that allow you to trim discretionary expenses during severe equity bear markets.
- Rebalance Annually: Maintain your strategic asset allocation (such as 60% equities and 40% fixed income) by trimming winning asset classes to replenish your cash reserves.
This article is for educational purposes only and should not be considered personalized financial advice. Consider consulting with a financial advisor or tax professional for guidance specific to your situation.
Frequently Asked Questions (FAQ)
What is the 4% rule for retirement?
The 4% rule is an empirical guideline stating that you can safely withdraw 4% of your investment portfolio in your first year of retirement, and then adjust that dollar amount annually for inflation. This framework was designed to preserve a balanced portfolio over a 30-year retirement horizon.
How do I calculate my retirement number using the 4% rule?
You calculate your target nest egg using the Rule of 25 by multiplying your expected annual retirement living expenses by 25. For example, if you anticipate needing $50,000 per year, your target portfolio is $1,250,000 ($50,000 multiplied by 25).
Is the 4% rule still valid today?
The 4% rule remains a strong baseline benchmark for traditional 30-year retirements. However, many financial planners recommend a more conservative initial rate of 3.25% to 3.50% for early retirees facing 40 to 50-year horizons, or adopting dynamic guardrail spending strategies.
What is sequence of returns risk in retirement?
Sequence of returns risk is the danger that severe market downturns occur in the early years of retirement while you are actively liquidating shares. Selling depressed assets locks in capital losses and permanently reduces the compounding base required to fund future years.
What are dynamic guardrail withdrawal strategies?
Dynamic guardrails, pioneered by financial planner William Guyton and William Klinger, adjust annual retirement distributions based on actual portfolio performance. Retirees increase spending by a bonus percentage during bull markets and skip inflation adjustments during major downturns.
For educational purposes. Consider your own circumstances before making financial decisions. Read our editorial policy.
From reading to planning
Explore the numbers for yourself.
Use our free calculators to compare scenarios and understand your options.