Long-Term vs Short-Term Capital Gains: Complete Tax Guide
Compare long-term vs short-term capital gains tax rates, the 366-day holding rule, 0%, 15%, and 20% brackets, and strategies to minimize your tax bill.
Generating investment profits is exciting, but retaining those gains requires understanding the tax code. Impatient investors who rapidly buy and sell securities often receive an expensive surprise from the Internal Revenue Service when filing their annual tax returns.
Key Takeaways
- Holding Period Threshold: Holding an appreciated investment for more than one year (at least 366 calendar days) unlocks preferential long-term capital gains rates of 0%, 15%, or 20%.
- Ordinary Income Drag: Liquidating an asset held for one year or less classifies profits as short-term capital gains, taxed at ordinary income rates up to 37%.
- Exact Calendar Rule: The holding period begins on the day following acquisition and must span past the one-year anniversary mark before execution.
- High-Earner Surtax: High-earning households face an additional 3.8% Net Investment Income Tax (NIIT) surtax on investment profits above statutory thresholds ($200,000 Single / $250,000 MFJ).
- Loss Offsetting Power: Realized capital losses offset capital gains dollar-for-dollar on Schedule D, with up to $3,000 in excess losses deductible against ordinary income annually.
Federal tax laws explicitly reward patient capital allocation while penalizing short-term speculative trading. Understanding how the calendar dictates your tax liability allows you to preserve thousands of dollars in investment compounding.
What Is the Difference Between Long-Term and Short-Term Capital Gains?
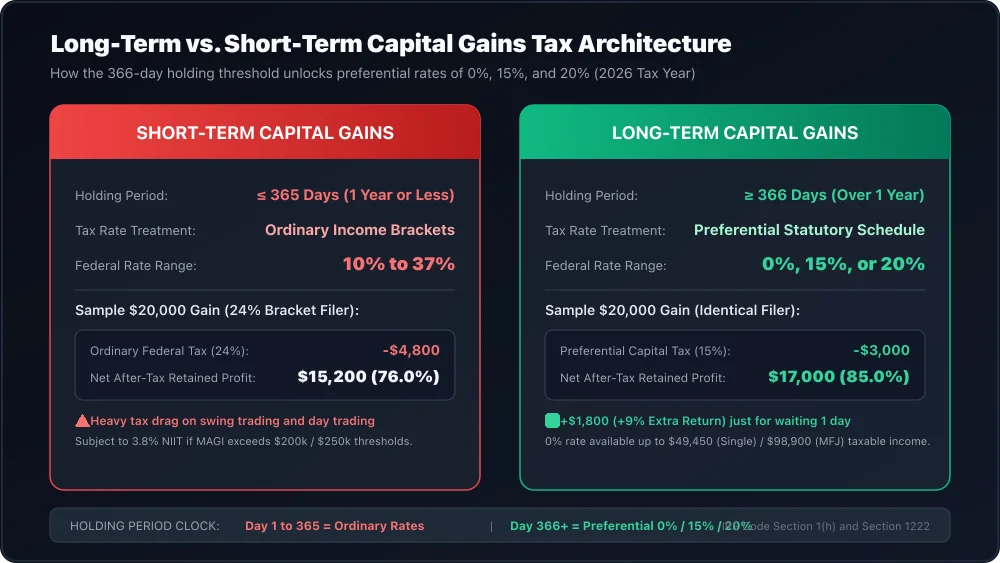
A short-term capital gain results from the sale of an asset held for one year or less and is taxed at ordinary federal income tax rates reaching up to 37%. A long-term capital gain applies to assets held for more than one year, unlocking preferential tax rates of 0%, 15%, or 20%.
When an investor sells a capital asset for more than its initial purchase price, known as the adjusted cost basis, a capital gain occurs. Tax treatment is governed strictly by the length of time the asset was owned. Statutory rules documented in IRS Topic No. 409 Capital Gains and Losses guidance establish the holding period standards that determine whether profits face ordinary income rates or preferential brackets.
This dual-track system applies to individual corporate equities, mutual funds, exchange-traded funds (ETFs), cryptocurrency tokens, real estate properties, and precious metals.
| Tax Characteristic | Short-Term Capital Gains (1 Year or Less) | Long-Term Capital Gains (More Than 1 Year) | Taxpayer Strategic Advantage |
|---|---|---|---|
| Applicable Federal Tax Rates | 10%, 12%, 22%, 24%, 32%, 35%, or 37% | 0%, 15%, or 20% preferential rates | Up to 17% lower federal tax drag |
| Tax Classification | Taxed as ordinary income (like salary) | Dedicated preferential capital gains schedule | Preserves compounding returns |
| Required Holding Period | Exactly 365 calendar days or fewer | 366 calendar days or longer | Waiting one day can save thousands |
| Net Investment Income Surtax | 3.8% applies if MAGI exceeds limits | 3.8% applies if MAGI exceeds limits | Top combined rate is 23.8% vs 40.8% |
Net Capital Gain / Loss = Net Proceeds (Gross Sale Price - Brokerage Fees) - Adjusted Cost Basis
Computes taxable realized capital gain or loss across securities, real estate, and digital assets.
Short-Term Capital Gains: Why Quick Profits Face Ordinary Income Tax Rates
The IRS taxes short-term gains as ordinary income, adding your trading profits directly to your wages, salaries, and tips. This treatment subjects short-term investors to their highest marginal tax bracket, creating significant tax drag on active trading strategies.
When day traders or swing investors book profits within a 12-month window, the government treats those earnings identically to a wage paycheck. Analyzing your effective tax burden through our guide on marginal vs effective tax rates shows that short-term gains are layered on top of earned salary, pushing profits into your highest applicable tax bracket. To track how ordinary income taxes affect take-home pay, review our detailed guide on understanding your paycheck stub.
For active traders in the 32% or 35% federal brackets, state income taxes can push the aggregate tax rate above 45%. This friction severely diminishes the mathematical advantage of active trading compared to passive long-term compounding.
Long-Term Capital Gains: The Preferential 0%, 15%, and 20% Tax Brackets
To incentivize patient capital investment in the economy, federal law taxes long-term gains at reduced brackets of 0%, 15%, and 20% based on taxable income thresholds. Married couples earning under six figures frequently qualify for the 0% capital gains bracket.
Investors can consult our practical strategies to lower your taxable income to position their taxable earnings within more favorable capital gains brackets. Filing guidelines from the Internal Revenue Service Schedule D Capital Gains and Losses portal outline the official income thresholds across individual filing categories.
The statutory income brackets for long-term capital gains are adjusted annually for inflation under IRS Revenue Procedure 2025-38:
| Filing Status | 0% Capital Gains Rate Bracket | 15% Capital Gains Rate Bracket | 20% Capital Gains Rate Bracket |
|---|---|---|---|
| Single Filers | Taxable income up to $49,450 | Taxable income $49,451 to $545,500 | Taxable income over $545,500 |
| Married Filing Jointly | Taxable income up to $98,900 | Taxable income $98,901 to $613,700 | Taxable income over $613,700 |
| Head of Household | Taxable income up to $66,250 | Taxable income $66,251 to $579,600 | Taxable income over $579,600 |
Most middle-class American households fall squarely into the 15% long-term capital gains bracket. Lower-income investors, college graduates starting careers, and early retirees living off dividends often qualify for the 0% bracket, eliminating federal tax liability entirely on substantial realized gains.
Tax Savings = Realized Gain × (Ordinary Marginal Tax Rate - Long-Term Capital Gains Rate)
Measures direct federal cash tax preserved by holding an appreciated security past 365 calendar days.
Simulate Your Capital Gains Tax Liability Model your net taxes across holding periods, cost basis methods, and state tax brackets using our interactive Capital Gains Tax Calculator. If you want to estimate how sheltering capital gains in tax-free accounts accelerates your wealth, test our Roth IRA Calculator.
The Calendar Rule: Exact Rules for Calculating the 366-Day Holding Period
Qualifying for long-term tax status requires holding an asset for more than one full year. The holding period begins on the day following purchase and must reach at least one year and one full calendar day before the trade execution date.
The IRS enforces an exact calendar rule detailed in IRS Publication 550 Investment Income and Expenses. When tracking your ownership period, the settlement date does not govern the holding clock. Instead, the official trade date dictates the timing:
- Day of Acquisition: Does not count toward the holding period. The clock starts on the calendar day immediately after purchase.
- The One-Year Mark: If you purchase a share on May 10th of Year 1, your one-year mark is May 10th of Year 2.
- Long-Term Qualification Date: Selling on May 10th of Year 2 results in a short-term capital gain. You must hold the security until at least May 11th of Year 2 (Day 366) to qualify for preferential long-term tax rates.
Selling just twenty-four hours too early can cost an investor thousands of dollars in unnecessary tax liabilities.
Cost Basis Accounting Methods: FIFO, Spec ID, and Average Cost
When selling a portion of your holdings in a company or index fund purchased at different prices over time, your accounting method determines your recognized gain.
- First-In, First-Out (FIFO): The default brokerage method. It assumes the oldest shares purchased are the first ones sold. In a rising market, FIFO generates the largest taxable capital gains because older shares typically have the lowest cost basis.
- Specific Identification (Spec ID): The optimal tax method. You instruct your brokerage to sell specific tax lots. This allows you to choose shares with the highest cost basis (to minimize immediate taxable gains) or shares held for more than 365 days (to ensure preferential long-term tax rates).
- Average Cost: Commonly used for mutual fund holdings. It averages the acquisition prices of all shares owned. Once elected for a mutual fund, switching back to specific identification requires formal IRS procedures.
Choosing Specific Identification over FIFO gives investors precision control over annual tax liabilities.
Tax-Loss Harvesting and the Wash-Sale Rule
Savvy investors optimize after-tax wealth by harvesting capital losses to offset recognized gains, monitoring the 3.8% Net Investment Income Tax surtax thresholds, and sheltering high-turnover investments inside tax-advantaged accounts.
Educational resources from the U.S. Securities and Exchange Commission Investor.gov Asset Allocation Guide emphasize that disciplined tax management plays a vital role in multi-decade wealth building.
How Capital Loss Offsetting Works on Schedule D
The IRS netting rules require taxpayers to follow a four-step sequence on Form 1040 Schedule D:
- Net Short-Term Holdings: Short-term gains and short-term losses are netted against each other.
- Net Long-Term Holdings: Long-term gains and long-term losses are netted against each other.
- Cross-Category Netting: If one category produces a net loss and the other produces a net gain, the excess loss offsets the remaining gain.
- Ordinary Income Offset: If total capital losses exceed total capital gains, taxpayers can deduct up to $3,000 of net losses against ordinary wages ($1,500 if married filing separately). Any remaining unused loss carries forward indefinitely into future tax years.
Allowable Ordinary Income Deduction = Min(Net Realized Capital Loss, $3,000)
Limits the annual capital loss write-off against salary and wage income under IRC Section 1211.
Navigating the 30-Day Wash-Sale Rule
The IRS Wash-Sale Rule (IRC Section 1091) disallows a capital loss deduction if you purchase a “substantially identical” stock or security within 30 days before or 30 days after the date of sale. This creates a 61-day window during which you cannot repurchase the same asset.
If a wash sale occurs:
- The disallowed loss is added to the cost basis of the newly repurchased security.
- The holding period of the original security is added to the holding period of the new security.
To maintain market exposure while harvesting losses, investors frequently sell an ETF tracking one benchmark (such as an S&P 500 fund) and immediately purchase an ETF tracking a different benchmark (such as a total stock market fund or Russell 1000 index).
Net Investment Income Tax (NIIT) and State Taxes
High earners face two additional tax layers that increase the total tax drag on capital gains.
Net Investment Income Tax (NIIT)
Enacted under IRC Section 1411, the NIIT imposes a 3.8% surtax on investment income for taxpayers whose Modified Adjusted Gross Income (MAGI) exceeds statutory thresholds:
- Single Filers: $200,000
- Married Filing Jointly: $250,000
- Married Filing Separately: $125,000
NIIT Liability = 3.8% × Min(Net Investment Income, MAGI - Statutory Threshold)
Federal surtax levied on capital gains, dividends, royalties, and passive rental income.
When NIIT applies, the top federal long-term capital gains rate increases from 20% to 23.8%, and the top short-term rate increases from 37% to 40.8%. Note that unlike standard tax brackets, the NIIT thresholds are not indexed for inflation, pulling more households into the surtax each year.
State Capital Gains Taxation
Most states do not provide preferential tax rates for long-term capital gains, taxing investment profits at ordinary state income tax rates:
- California: Taxes capital gains as regular income up to 13.3%, yielding a top combined federal and state long-term rate of 37.1%.
- New York: Combines state tax rates up to 10.9% with New York City local tax (up to 3.876%), resulting in combined top rates over 38%.
- Washington State: While lacking a general personal income tax, Washington levies a 7% state excise tax on long-term capital gains exceeding statutory deductions ($270,000 adjusted for inflation).
- No-Tax States: States including Florida, Texas, Nevada, and Tennessee levy zero state capital gains tax, allowing investors to retain full after-federal returns.
Case Study: Sarah’s $10,000 Capital Gain Tax Comparison
To evaluate how holding periods alter financial outcomes, consider Sarah, age 32, a corporate technology manager earning $150,000 in taxable salary. This income places Sarah in the 24% federal marginal ordinary income tax bracket.
Sarah purchased 100 shares of an enterprise cloud company in January of Year 1 for $10,000. By October of Year 1, the shares appreciated to $20,000. Sarah faced a decision: lock in profits at 10 months or hold until February of Year 2 (13 months).
Comparing her after-tax proceeds highlights the impact of the holding period:
| Transaction Metric | Scenario A: 10-Month Short-Term Sale | Scenario B: 13-Month Long-Term Sale | Net Taxpayer Gain |
|---|---|---|---|
| Gross Investment Profit | $10,000 capital gain | $10,000 capital gain | Identical gross profit |
| Federal Tax Rate Applied | 24% ordinary marginal rate | 15% preferential long-term rate | 9% lower tax rate |
| Federal Tax Liability | $2,400 paid to IRS | $1,500 paid to IRS | $900 in tax cash saved |
| Net After-Tax Proceeds | $7,600 retained profit | $8,500 retained profit | +$900 after-tax wealth |
| Effective Net Return | +76.0% net gain on capital | +85.0% net gain on capital | +11.8% boost in net return |
By waiting an additional three months to cross the 366-day holding threshold, Sarah saved $900 in federal taxes on an identical $10,000 gain.
Projecting the growth of that $900 reinvested over thirty years using compound interest principles demonstrates that patient holding habits add tens of thousands of dollars to terminal retirement balances.
Frequently Asked Questions About Capital Gains Taxes
What is the difference between a long-term and short-term capital gain?
A long-term capital gain applies to profits from the sale of an asset held for more than one full year, qualifying for preferential federal rates of 0%, 15%, or 20%. A short-term capital gain applies to assets held for one year or less and is taxed at ordinary federal income tax rates reaching up to 37%.
How is the holding period calculated for capital gains?
The IRS holding period clock begins on the day after you acquire the security and ends on the exact trade date the sale executes. To qualify for long-term status, your asset holding period must exceed 365 calendar days.
What is the Net Investment Income Tax surtax?
The Net Investment Income Tax (NIIT) is an additional 3.8% federal surtax levied on investment income for high earners with modified adjusted gross income exceeding $200,000 for single filers or $250,000 for married couples filing jointly. This surtax applies to both short-term and long-term capital gains above the income thresholds.
Can capital losses offset capital gains taxes?
Yes, realized capital losses offset capital gains dollar-for-dollar on IRS Schedule D, matching short-term losses against short-term gains and long-term losses against long-term gains. If net losses exceed gains, taxpayers can deduct up to $3,000 against ordinary salary and carry forward the remainder indefinitely.
Do state income taxes apply to capital gains?
Most states tax both short-term and long-term capital gains as standard state ordinary income without offering preferential rates. Taxpayers residing in high-tax jurisdictions must account for combined federal and state liabilities when planning asset sales.
This article is for educational purposes only and should not be considered personalized financial advice. Consider consulting with a financial advisor or tax professional for guidance specific to your situation.
For educational purposes. Consider your own circumstances before making financial decisions. Read our editorial policy.
From reading to planning
Explore the numbers for yourself.
Use our free calculators to compare scenarios and understand your options.