Understanding Your Paycheck Stub: Taxes and Deductions Guide
Understand your paycheck stub line by line. See where each dollar goes on a real $3,000 paycheck, from FICA to 401(k), and adjust your W-4 to keep more.
Receiving a regular paycheck represents the primary financial milestone for working professionals across every economic sector. However, opening an electronic earnings statement often generates immediate confusion when top-line earnings diverge significantly from final deposited balances. Understanding your paycheck stub transforms an obscure administrative document into an actionable blueprint for personal financial optimization.
Key Takeaways
- Gross vs. Net Pay: Gross pay measures total earned compensation, whereas net pay reflects the actual cash deposited after mandatory withholdings and elective benefits.
- FICA Contributions: Federal Insurance Contributions Act (FICA) taxes require a 6.2% Social Security deduction up to the 2026 statutory wage base ($184,500) and a 1.45% uncapped Medicare deduction.
- Pre-Tax Advantage: Pre-tax deductions for retirement accounts, health insurance premiums, and HSAs reduce your taxable wage base before federal and state income tax brackets apply.
- Form W-4 Alignment: Aligning Form W-4 withholding entries with actual household filing status prevents substantial unexpected tax liabilities or excessive zero-interest loans to the IRS.
According to data published by the Bureau of Labor Statistics Usual Weekly Earnings of Wage and Salary Workers, full-time wage and salary workers maintain median weekly earnings exceeding $1,145. When payroll deductions consume 25% to 40% of those earnings, identifying the destination of each dollar becomes essential for long-term balance sheet stability.
Gross Pay vs. Net Pay: Understanding the Core Difference
Gross pay represents the total financial compensation an employer agrees to pay before any mandatory taxes or elective benefit reductions take effect. Net pay represents the remaining liquid balance that transfers into a personal bank account on scheduled distribution dates.
For salaried professionals, gross earnings divide evenly across annual pay cycles, such as 24 semi-monthly periods or 26 biweekly distributions. Hourly workers calculate gross compensation by multiplying regular hours by established wage rates, adding statutory time-and-a-half multipliers for hours surpassing standard 40-hour thresholds.
Net pay, frequently termed take-home pay, dictates household purchasing power and monthly living budgets. The numerical distance between gross and net pay represents statutory tax withholdings combined with elective employee benefit elections.
Net Take-Home Pay = Gross Earnings - Statutory Taxes - Pre-Tax Deductions - Post-Tax Deductions
Determines actual direct-deposit cash flow transferred to your bank account each pay period.
Reviewing this mathematical gap allows individuals to recognize whether lower cash flow stems from external tax liabilities or intentional investments in retirement security. Monitoring gross pay also ensures employers properly credit performance bonuses, sales commissions, and overtime hours.
Simulate Your Net Paycheck Withholdings Model your net pay across federal brackets, state withholdings, and pre-tax deductions using our interactive Gross to Net Paycheck Calculator. If you are negotiating an hourly wage or reviewing overtime shifts, translate your hourly rate into annual earnings with our Hourly to Salary Calculator.
Mandatory Payroll Taxes: Federal, State, and Local Withholding
Mandatory payroll taxes represent statutory obligations enacted by federal, state, and municipal governing bodies to fund public infrastructure and civic programs. Employers function as legal withholding agents, collecting these sums directly from paychecks and remitting them to appropriate revenue services.
Federal income tax withholding forms the largest compulsory deduction for most American workers. The United States maintains a progressive tax schedule where higher tiers of income face escalating marginal percentages ranging from 10% to 37%. Understanding marginal vs effective tax rates helps employees comprehend why additional earnings do not result in lower overall take-home earnings.
Employers calculate federal withholding by referencing IRS withholding tables alongside the employee’s submitted Form W-4 data. The Internal Revenue Service Publication 15-T Federal Income Tax Withholding Methods provides employers with exact computational methods for percentage and wage-bracket withholding calculations.
State income taxes mirror federal structures in many jurisdictions, though statutory tax designs vary widely across geographic boundaries:
- No-Tax States: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming impose no state levy on earned wage income.
- Flat-Tax States: Jurisdictions such as Colorado, Illinois, Indiana, and Pennsylvania apply a single statutory percentage to all taxable earnings.
- Progressive-Tax States: States such as California, New York, and New Jersey apply graduated brackets that can reach above 10% for high earners.
Municipalities and counties may also assess local earnings taxes or school district surcharges. Cities such as New York City, Philadelphia, and Columbus deduct specialized municipal taxes to maintain urban municipal infrastructure.
How FICA Taxes Work: Social Security and Medicare Contributions
Federal Insurance Contributions Act (FICA) taxes represent compulsory payroll contributions designed to finance federal social safety net programs for retirees and disabled citizens. Unlike general income taxes, FICA withholdings target specific trust funds managed by the federal government.
The FICA statutory framework consists of two distinct components assessed against earned employee wages:
Total FICA Tax = (Eligible Wages × 6.2% [up to $184,500]) + (Eligible Wages × 1.45%)
Computes mandatory employee contributions toward Social Security OASDI and Medicare Hospital Insurance.
The first component funds Old-Age, Survivors, and Disability Insurance (OASDI), commonly known as Social Security. Employees contribute 6.2% of gross earnings toward OASDI until reaching the annual contribution threshold.
According to statutory guidelines from the Social Security Administration Contribution and Benefit Base, wages exceeding the statutory taxable threshold ($184,500 for the 2026 tax year) are completely exempt from further Social Security tax withholdings for the remainder of that calendar year. This cap resets annually on January 1. High earners who cross this threshold notice an automatic 6.2% boost in net take-home pay during the final months of the year.
The second component funds Medicare Hospital Insurance, requiring a mandatory 1.45% withholding from all earned wages without an income ceiling. An additional 0.9% Medicare surtax applies to individual compensation surpassing $200,000, or $250,000 for married couples filing jointly. Employers do not match the additional 0.9% surtax.
Employers must match standard employee FICA contributions dollar for dollar, paying an identical 6.2% for Social Security and 1.45% for Medicare. Self-employed freelancers and business owners pay both halves, totaling 15.3% in self-employment taxes, though half is deductible on Form 1040. For independent worker strategies, explore our comprehensive breakdown of W-2 employee vs 1099 contractor economics.
| Payroll Tax Element | Employee Rate | Employer Match | Wage Limit Application |
|---|---|---|---|
| Social Security (OASDI) | 6.20% | 6.20% | Capped at $184,500 (2026 tax year) |
| Medicare Part A | 1.45% | 1.45% | No wage ceiling (applies to all wages) |
| Additional Medicare Surtax | 0.90% | 0.00% | Single wages over $200k / Joint over $250k |
| Federal Income Tax | 10% to 37% | None | Progressive brackets based on Form W-4 |
Strategic Deductions: Pre-Tax vs. Post-Tax Benefit Options
Elective payroll deductions represent voluntary elections chosen by employees to acquire fringe benefits, protect family health, and accumulate long-term retirement wealth. Distinguishing between pre-tax and post-tax deductions dictates how efficiently an employee minimizes current taxable liabilities.
Pre-tax deductions are subtracted directly from gross earnings prior to calculating federal, state, and local income tax withholdings. By reducing adjusted gross wages, these contributions directly decrease the total tax liability assessed on each pay cycle. Exploring methods for legally reducing your taxable income through deductions reveals substantial annual cash savings.
Immediate Tax Savings = Contribution Amount × Marginal Income Tax Rate
Calculates direct federal income tax reduction achieved per pay period through pre-tax benefit elections.
Standard pre-tax deductions include:
- Retirement Plans: Traditional 401(k) and 403(b) elective deferrals shield income from federal and state income taxes, though FICA taxes still apply.
- Section 125 Cafeteria Plans: Employer-sponsored health, dental, and vision insurance premiums, alongside Flexible Spending Accounts (FSAs), are exempt from both income taxes and FICA payroll taxes.
- Health Savings Accounts (HSAs): Contributions made through payroll deduction to an HSA enjoy triple tax advantages, escaping federal income tax, state income tax (in 48 states), and FICA taxes. For a complete strategy, read our analysis on why the HSA is the best retirement account.
Post-tax deductions occur after all mandatory federal, state, and payroll taxes have been assessed against gross compensation. Because post-tax items utilize net dollars, they provide zero immediate reduction in current calendar tax liability:
- Roth 401(k) Contributions: Fund retirement with after-tax dollars in exchange for 100% tax-free distributions in retirement.
- Supplemental Disability and Life Insurance: Paying disability insurance with post-tax dollars ensures that any future disability benefit payouts remain entirely tax-free.
- Direct Charitable Payroll Giving: Donating post-tax dollars directly from payroll to designated non-profit organizations.
| Deduction Type | Tax Timing Treatment | Take-Home Impact | Future Benefit Structure |
|---|---|---|---|
| Traditional 401(k) | Pre-Tax (FIT/SIT) | Reduces current tax bite | Taxable as ordinary income in retirement |
| Roth 401(k) | Post-Tax | Full tax paid today | 100% tax-free withdrawals in retirement |
| Health Insurance Premium | Pre-Tax (Section 125) | Exempt from income & FICA | Immediate healthcare network coverage |
| Disability Coverage | Post-Tax | Paid from net earnings | Disability benefit payouts remain tax-free |
| Health Savings Account | Pre-Tax (Triple-Advantaged) | Shields income & FICA | Tax-free medical care across entire lifetime |
Case Study: Analyzing a Biweekly $3,000 Paycheck Line by Line
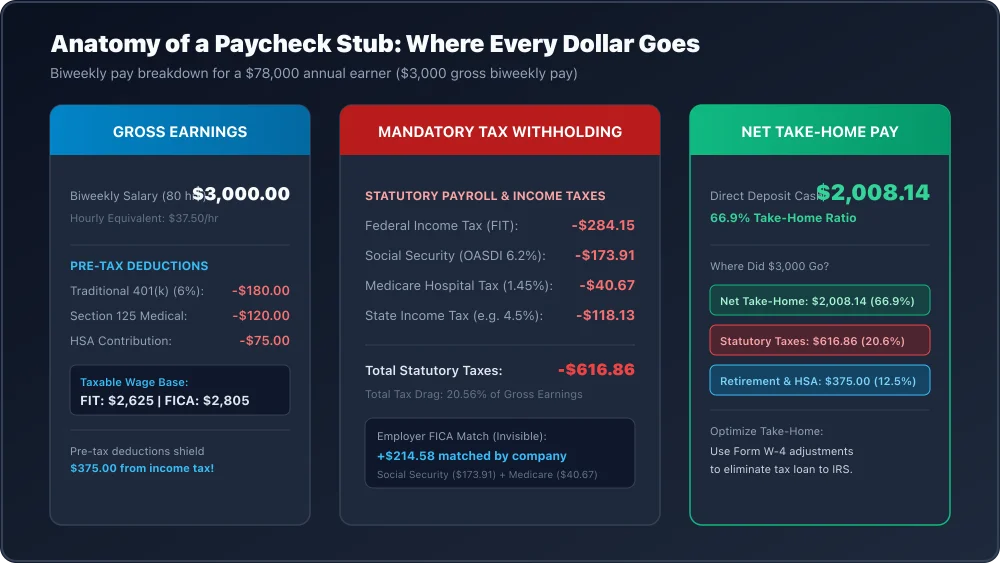
Examining an authentic numerical scenario clarifies how various payroll deductions interact to convert top-line gross salary into final liquid deposits. Consider the pay statement for Marcus, a corporate marketing specialist residing in a state with a 4.5% flat income tax rate.
Marcus earns an annual base salary of $78,000, distributed across 26 biweekly pay periods. His resulting gross pay equals exactly $3,000.00 per pay cycle. Marcus contributes 6% of his gross pay ($180.00) to a traditional 401(k) plan to capture his full employer match, pays $120.00 biweekly toward employer medical insurance under a Section 125 cafeteria plan, and deposits $75.00 into a Health Savings Account.
Let us trace how payroll software computes Marcus’s take-home pay:
- Gross Earnings: $3,000.00 (80 hours at $37.50/hour).
- Section 125 Pre-Tax Deductions: $120.00 (Medical) + $75.00 (HSA) = $195.00. These deductions reduce both income tax and FICA tax bases.
- FICA Taxable Base: $3,000.00 - $195.00 = $2,805.00.
- Social Security (6.2%): $2,805.00 × 0.062 = $173.91
- Medicare (1.45%): $2,805.00 × 0.0145 = $40.67
- Income Tax Pre-Tax Deductions: $180.00 (401k) + $195.00 (Medical/HSA) = $375.00.
- Federal & State Taxable Wage Base: $3,000.00 - $375.00 = $2,625.00.
- Federal Income Tax Withholding: $284.15 (calculated via IRS Pub 15-T percentage tables).
- State Income Tax Withholding (4.5%): $2,625.00 × 0.045 = $118.13.
- Total Mandatory Taxes: $173.91 + $40.67 + $284.15 + $118.13 = $616.86.
- Total Pre-Tax Deductions: $180.00 + $120.00 + $75.00 = $375.00.
- Net Deposited Pay: $3,000.00 - $616.86 - $375.00 = $2,008.14.
| Paycheck Line Item | Transaction Category | Calculation Basis | Balance Amount |
|---|---|---|---|
| Gross Earnings | Earned Compensation | Regular Biweekly Salary (80 hrs) | +$3,000.00 |
| Traditional 401(k) | Pre-Tax Deduction | 6.0% of Gross Base | -$180.00 |
| Medical Insurance Plan | Pre-Tax (Section 125) | Employer Group Premium | -$120.00 |
| Health Savings Account | Pre-Tax (Section 125) | Elective HSA Contribution | -$75.00 |
| Federal Income Tax | Mandatory Withholding | Progressive Table Rate | -$284.15 |
| State Income Tax | Mandatory Withholding | 4.5% Taxable State Base | -$118.13 |
| Social Security (OASDI) | Mandatory Payroll Tax | 6.20% on $2,805 Wage Base | -$173.91 |
| Medicare Hospital Tax | Mandatory Payroll Tax | 1.45% on $2,805 Wage Base | -$40.67 |
| Net Pay / Direct Deposit | Liquid Cash Balance | Final Bank Transfer | $2,008.14 |
Marcus takes home $2,008.14, representing a 66.9% net take-home ratio. His pre-tax elections saved him $82.50 in immediate federal and state income taxes on this single paycheck ($375 pre-tax × 22% marginal FIT + 4.5% SIT).
Reviewing the protections outlined by the Consumer Financial Protection Bureau depository account protections ensures direct deposits land safely in federally insured banking facilities.
How to Adjust Form W-4 to Optimize Take-Home Cash Flow
IRS Form W-4 informs employers how much federal income tax should be withheld from each paycheck throughout the calendar year. Completing this form accurately prevents taxpayers from facing massive tax penalties while eliminating excessive overwithholding.
Receiving a substantial tax refund each spring often feels like a financial victory, but it actually signifies that you granted the government an interest-free loan throughout the preceding twelve months. Adjusting withholding allowances redirects that capital back into every biweekly paycheck, allowing households to accelerate emergency fund growth, eliminate credit card debt, or invest earlier.
Form W-4 uses direct monetary entries across five core steps:
- Step 1: Personal Information: Enter name, address, Social Security number, and federal filing status (Single, Married Filing Jointly, Head of Household).
- Step 2: Multiple Jobs or Working Spouse: Complete this step if you hold more than one job simultaneously or are married filing jointly and both spouses work. Failure to coordinate Step 2 is the number one cause of unexpected year-end tax bills for two-income couples.
- Step 3: Claim Dependent Credits: Enter $2,000 for each qualifying child under age 17 and $500 for other dependents. This directly reduces annual tax withholding dollar-for-dollar across paychecks.
- Step 4: Other Adjustments:
- 4(a): Other non-wage income (dividends, interest, freelance) you want tax withheld for.
- 4(b): Deductions exceeding the standard deduction to reduce withholding.
- 4(c): Extra dollar withholding requested per pay period.
- Step 5: Signature: Sign and date the document.
Employees should re-evaluate their Form W-4 whenever encountering substantial personal milestones, including marriage, divorce, home purchases, or changes in retirement savings rates. To audit the hourly and premium pay lines on your own earnings statement, verify your base rate in our Salary to Hourly Calculator and double-check FLSA premium hours in the Overtime Calculator or Time and a Half Calculator. For end-of-year tax deductions that you can claim on Schedule A, consult our comprehensive catalog of common tax deductions.
Frequently Asked Questions About Paycheck Stubs
What is the primary difference between gross pay and net pay?
Gross pay represents the total compensation earned before any payroll taxes or elective deductions are removed. Net pay represents the remaining cash deposited into an employee bank account after all withholdings are subtracted.
What specific programs do FICA taxes fund?
FICA taxes fund the federal Social Security retirement and disability program alongside Medicare hospital insurance. Employees pay a combined 7.65% payroll contribution that is matched equally dollar for dollar by their employer.
How do pre-tax deductions lower total tax liability?
Pre-tax deductions are subtracted directly from gross earnings prior to calculating federal and state income tax withholding. This reduces adjusted gross earnings and immediately shields that portion of income from statutory tax brackets.
When should an employee submit a revised Form W-4?
Employees should submit a revised Form W-4 whenever experiencing significant life changes such as marriage, childbirth, divorce, or secondary income shifts. Updating withholding allowances ensures accurate annual tax obligations without triggering underpayment penalties.
Is overtime pay taxed at a higher percentage rate than regular pay?
Overtime compensation is not subject to a higher statutory tax rate, though it may trigger higher withholding because payroll software annualizes the larger pay period. Any excess withholding is reconciled and refunded when filing an annual tax return.
This article is for educational purposes only and should not be considered personalized financial advice. Consider consulting with a financial advisor or tax professional for guidance specific to your situation.
For educational purposes. Consider your own circumstances before making financial decisions. Read our editorial policy.
From reading to planning
Explore the numbers for yourself.
Use our free calculators to compare scenarios and understand your options.