7 Common Tax Deductions You Might Be Missing Out On
Review 7 often-missed tax deductions, including HSA and IRA contributions, educator expenses, and SALT limits, to legally lower your federal tax bill.
Most taxpayers treat annual tax season like a visit to the dentist: a necessary evil filled with anxiety, confusion, and the resigned acceptance of an uncomfortable outcome. Filers gather their tax forms, enter numbers into tax software, and hope for a modest refund check, unaware that they may be leaving hundreds or thousands of dollars in legitimate write-offs on the table.
The Internal Revenue Service does not reach out to remind you about deductions you forgot to claim. Your final tax bill reflects your strategic understanding of the tax code, and passivity is an expensive choice.
Key Takeaways
- Tax deductions reduce your taxable income before brackets apply, saving you money proportionally to your marginal tax bracket.
- Above-the-line deductions on Schedule 1 can be claimed even when taking the standard deduction, directly reducing your Adjusted Gross Income (AGI).
- Health Savings Accounts (HSAs) provide a triple-tax advantage with 2026 statutory limits of $4,400 for self-only and $8,750 for family plans.
- Under statutory provisions, the State and Local Tax (SALT) deduction cap is adjusted to $40,400 for 2026 before phasing down for high earners.
Understanding the Fundamentals: Tax Deductions vs. Tax Credits
Before examining individual write-offs, filers must understand how deductions interact with federal tax brackets:
Taxable Base Reduction = Qualified Above-the-Line Adjustments + Standard or Itemized Deduction
Net Tax Savings = Deductible Expenditure × Marginal Tax Rate Bracket
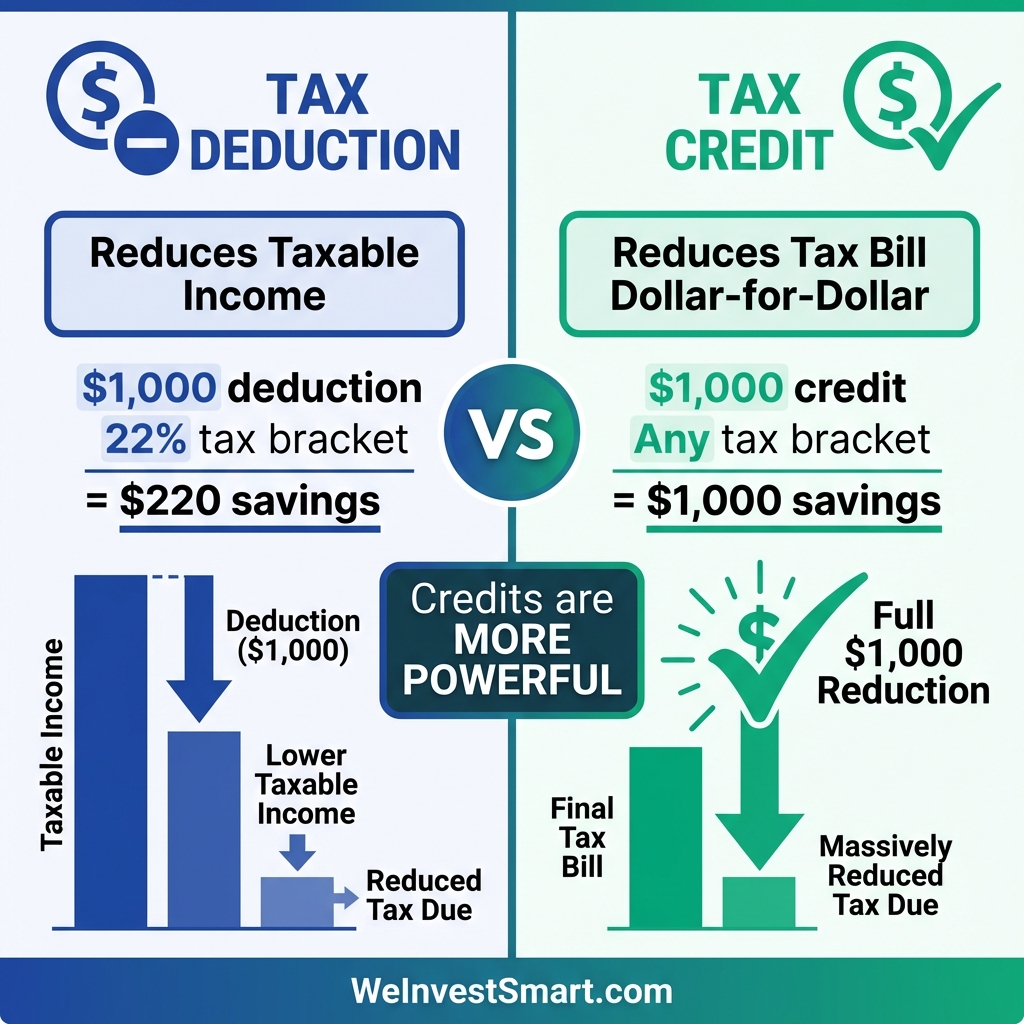
A tax deduction reduces your taxable income. If you fall within the 22% marginal tax bracket, a $1,000 tax deduction reduces your tax liability by $220 ($1,000 × 0.22).
A tax credit, by contrast, provides a direct dollar-for-dollar reduction of your final calculated tax obligation. A $1,000 tax credit knocks $1,000 directly off what you owe. While credits deliver powerful direct savings, combining multiple above-the-line and itemized deductions significantly lowers your base taxable income.
Many valuable write-offs are classified as above-the-line deductions. You do not need to itemize on Schedule A to claim them, allowing you to capture the full standard deduction and these targeted adjustments simultaneously.
Understanding your marginal versus effective tax rate clarifies how each incremental dollar of deductions saves money at your highest statutory bracket.
Model Your Deductions: Run your earnings through our Gross-to-Net Paycheck Calculator to calculate take-home pay, or estimate state tax write-offs with our New Jersey Sales Tax Calculator.
Above-the-Line vs. Below-the-Line: The Strategic Difference
Tax deductions fall into two distinct legal categories: above-the-line adjustments and below-the-line itemized deductions. Understanding this distinction is essential for tax planning.
Above-the-line deductions appear on IRS Form 1040 Schedule 1 (Part II). They subtract directly from your total gross income to determine your Adjusted Gross Income (AGI). Because these adjustments reduce your AGI itself, they provide substantial secondary benefits:
- They lower the statutory 7.5% AGI hurdle required to deduct out-of-pocket medical expenses.
- They preserve eligibility for income-restricted tax credits like the Child Tax Credit and Lifetime Learning Credit.
- They reduce state taxable income in states that use federal AGI as their starting calculation baseline.
Below-the-line deductions, by contrast, appear on IRS Form 1040 Schedule A. They are subtracted from your AGI only if you choose to itemize rather than claiming the standard deduction ($16,100 for single filers, $32,200 for married couples filing jointly in 2026). If your total below-the-line expenses do not exceed the standard deduction threshold, itemizing provides zero additional financial benefit.
7 Commonly Overlooked Tax Deductions
Reviewing these seven high-impact deductions ensures you capture every eligible dollar before finalizing your tax return:
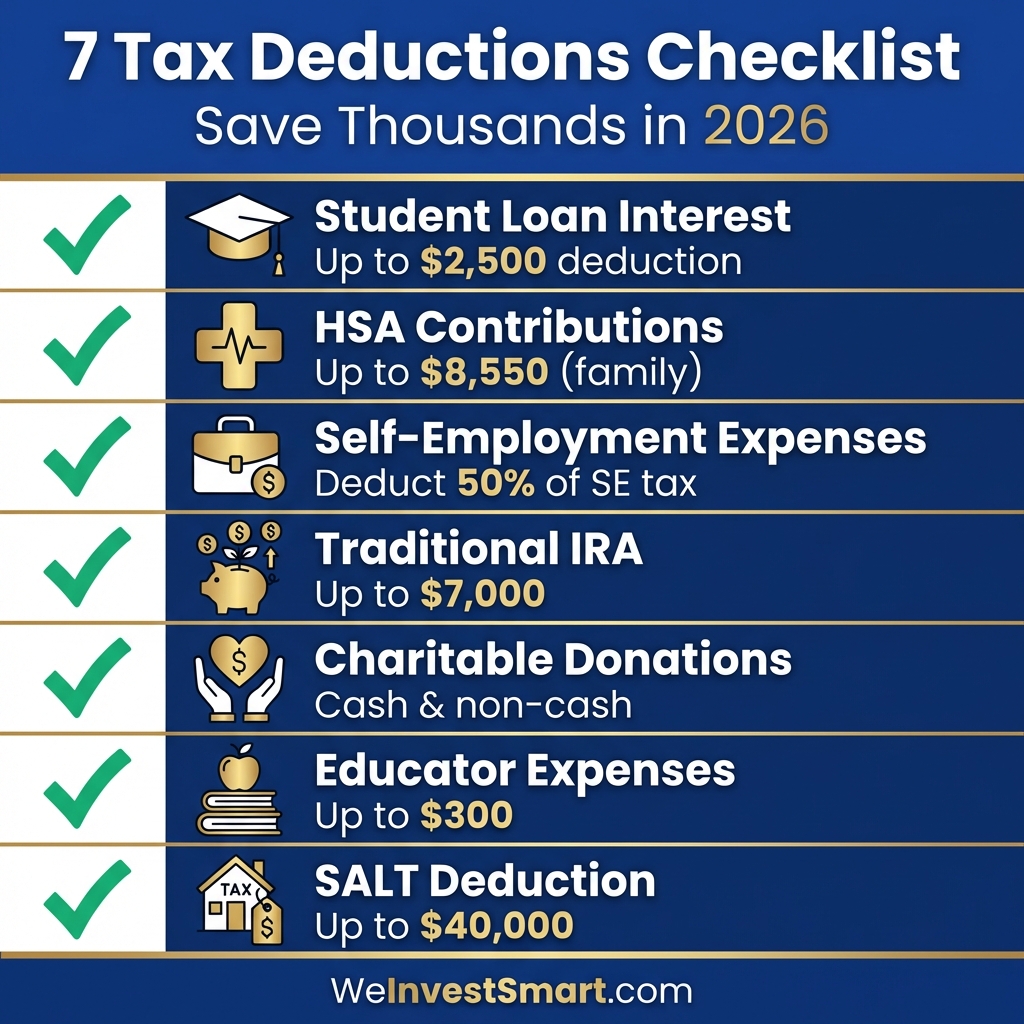
1. The Student Loan Interest Deduction
Borrowers repaying higher education debt can deduct up to $2,500 per year in qualified student loan interest under IRS Topic No. 456. Because this is an above-the-line deduction, you can claim it without itemizing on Schedule A.
If you paid $2,500 in eligible loan interest and fall into the 22% federal tax bracket, this deduction reduces your tax bill by $550. Your loan servicer will issue IRS Form 1098-E if you paid $600 or more in interest during the calendar year. Even if family members assisted with payments, the borrower who remains legally obligated on the promissory note can claim the deduction. For the 2026 tax year, the deduction phases out across specified Modified AGI thresholds ($85,000 to $100,000 for single filers; $170,000 to $200,000 for married couples filing jointly).
2. Health Savings Account (HSA) Contributions
Health Savings Accounts offer an exceptional triple-tax advantage under IRS Publication 969. Contributions are 100% tax-deductible, account balances invest and compound tax-free, and withdrawals used for qualified healthcare expenses incur zero federal or state income tax.
Under IRS Revenue Procedure 2025-19, the statutory annual contribution limit for the 2026 tax year is $4,400 for self-only coverage and $8,750 for family coverage. Individuals age 55 and older can contribute an additional $1,000 catch-up contribution. Contributions made via workplace payroll deductions bypass income and FICA payroll taxes automatically. Post-tax personal deposits qualify as an above-the-line deduction on Form 1040 Schedule 1. Review our complete guide to HSA retirement strategies to maximize compounding growth.
3. Self-Employment Business Expenses
Contractors, freelancers, and side-hustle operators can deduct all ordinary and necessary operational expenses on IRS Form 1040 Schedule C under IRS business expense regulations.
Under Internal Revenue Code Section 164(f), self-employed individuals deduct 50% of their calculated 15.3% self-employment tax directly on Schedule 1. Independent professionals can also write off health insurance premiums, professional equipment, specialized software, and dedicated home office square footage. Review our W-2 employee vs 1099 contractor comparison to analyze self-employment tax calculations in detail.
When calculating vehicle write-offs, contractors can choose between actual operating expenses (fuel, depreciation, insurance) or the IRS standard mileage rate (72.5 cents per business mile for 2026). Dedicated home office spaces qualify for either the simplified deduction of $5 per square foot (up to 300 square feet) or the actual prorated expense method.
4. Traditional IRA Contributions
Taxpayers without access to workplace retirement plans, or those falling within statutory income limits, can deduct contributions to a traditional individual retirement account under IRS IRA contribution limits. For the 2026 tax year, eligible individuals can contribute up to $7,000 ($8,000 for savers age 50 and older).
If you are not covered by an employer retirement plan at work, your full traditional IRA contribution is deductible regardless of income. If you participate in a workplace 401(k), the deduction phases out across statutory MAGI brackets. If you execute non-deductible contributions for retirement savings, review our guide on the Backdoor Roth pro-rata rule and Form 8606 to avoid double taxation.
5. Charitable Donations (Cash, Property, and Non-Cash Gifts)
Taxpayers who itemize deductions on Schedule A can deduct cash donations and fair-market-value property gifts to qualified 501(c)(3) non-profit organizations.
Non-cash contributions of clothing, furniture, and household goods dropped off at recognized charitable donation centers provide substantial write-offs. For any non-cash donation exceeding $500, filers must file IRS Form 8283. Single items valued above $5,000 generally require a qualified written appraisal. For filers claiming the standard deduction, the tax code provides a separate above-the-line charitable deduction of up to $1,000 for single filers ($2,000 for married couples filing jointly).
Taxpayers age 70½ and older who hold traditional IRAs can execute Qualified Charitable Distributions (QCDs) of up to $111,000 per year directly to qualified non-profits. QCDs satisfy annual Required Minimum Distributions (RMDs) while excluding the distribution from taxable gross income entirely.
6. The Educator Expense Deduction
Eligible primary and secondary school educators can deduct up to $300 of unreimbursed out-of-pocket classroom supplies, instructional software, and books. If both spouses are eligible educators filing a joint tax return, the maximum deduction is $600 ($300 per qualifying spouse).
Because this adjustment is located above-the-line on Form 1040 Schedule 1, teachers, instructors, counselors, and aides can claim this deduction without needing to itemize on Schedule A. Qualified expenses include supplementary reading materials, lab supplies, educational computer hardware, and professional development courses directly related to curriculum instruction.
7. State and Local Tax (SALT) Deduction
Taxpayers who itemize can deduct state and local income taxes (or general sales taxes) plus real estate and personal property taxes under IRS Topic No. 503.
Under statutory tax revisions, the total SALT deduction cap is adjusted to $40,400 for the 2026 tax year (up from the historical $10,000 limitation), subject to phase-outs for high earners. For homeowners in states with significant property or income taxes, this adjustment provides a major incentive to evaluate itemizing against the standard deduction. Explore our tax planning guides on lowering taxable income to structure itemized deductions effectively.
Medical Expenses: Understanding the 7.5% AGI Threshold
One of the most frequently misunderstood itemized write-offs is the deduction for unreimbursed medical and dental expenses under Internal Revenue Code Section 213.
Taxpayers can deduct qualifying medical and dental expenses only to the extent that the total out-of-pocket costs exceed 7.5% of their Adjusted Gross Income. For example, if a household reports an AGI of $100,000, the first $7,500 of medical expenses is non-deductible. If their total qualified medical bills equal $12,000, they can deduct $4,500 on Schedule A ($12,000 - $7,500).
Qualifying expenses include:
- Prescription medications and insulin.
- Payments to doctors, dentists, surgeons, chiropractors, and psychiatrists.
- Inpatient hospital care and residential nursing home care costs primarily for medical treatment.
- Prescription eyeglasses, contact lenses, hearing aids, and guide dogs.
- Medically necessary home improvements, such as installing wheelchair ramps or widening doorways.
Because the 7.5% hurdle is high, aggressive medical deduction planning works best in years with major surgeries or extensive dental procedures, particularly when paired with high above-the-line deductions that lower the underlying AGI floor.
Deduction Bunching: A Multi-Year Strategy for Homeowners
With the standard deduction set at $16,100 for individuals and $32,200 for joint filers in 2026, many households discover that their annual deductible expenses hover just below the itemizing threshold. For example, a married couple paying $18,000 in property taxes and mortgage interest plus $5,000 in annual charitable donations totals $23,000 in expenses, falling short of the $32,200 standard deduction.
The solution is deduction bunching: intentionally concentrating two years of deductible expenses into a single tax year while taking the standard deduction in alternate years:
| Year | Strategy | Deductible Actions | Deduction Claimed | Total Tax Savings |
|---|---|---|---|---|
| Year 1 | Bunch Itemized Deductions | Prepay property taxes, double charitable gifts into a Donor-Advised Fund ($10,000 total gifts), pay scheduled dental expenses | $38,000 Itemized (Exceeds $32,200 threshold) | Maximizes write-offs above the standard deduction |
| Year 2 | Take Standard Deduction | Make minimal charitable gifts, pay routine expenses as scheduled | $32,200 Standard | Receives full statutory allowance without extra spending |
| Two-Year Total | Strategic Alternation | Same total cash outflow over 24 months | $70,200 Cumulative | Saves thousands compared to taking standard deduction both years |
Utilizing a Donor-Advised Fund (DAF) enables donors to contribute multiple years of charitable gifts in Year 1 to capture the upfront itemized deduction, while distributing the grants to non-profit charities gradually across future years.
Complete Summary: Tax Deductions Cheat Sheet
| Tax Deduction | Deduction Type | IRS Form / Schedule | 2026 Statutory Limit | Key Qualification Rules |
|---|---|---|---|---|
| Student Loan Interest | Above-the-Line | Form 1040 Schedule 1 | $2,500 | Phases out between $85k–$100k MAGI (single) |
| HSA Contributions | Above-the-Line | Form 8889 / Schedule 1 | $4,400 Single / $8,750 Family | Requires qualifying HDHP; +$1,000 catch-up at 55+ |
| Traditional IRA | Above-the-Line | Form 1040 Schedule 1 | $7,000 / $8,000 (age 50+) | Income phaseouts apply if covered by workplace 401(k) |
| Self-Employment Write-Offs | Business Adjustment | Schedule C & Schedule 1 | 100% of Ordinary Expenses | Includes 50% SECA tax, health premiums, home office |
| Educator Expenses | Above-the-Line | Form 1040 Schedule 1 | $300 Single / $600 Joint | Requires 900+ hours in K-12 school during school year |
| State & Local Taxes (SALT) | Itemized | Form 1040 Schedule A | $40,400 cap | State income or sales tax plus real estate taxes |
| Charitable Gifts | Itemized / Above-the-Line | Schedule A / Form 1040 | 60% AGI limit ($1k non-itemizer) | Written receipts required for gifts of $250 or more |
Strategic Action Plan: How to Track and Claim Your Deductions
To ensure you never miss eligible tax write-offs, implement this structured tracking system:
- Establish a Dedicated Digital Tax Folder: Create subfolders for Form 1098 mortgage interest, Form 1098-E student loan interest, Form 1099-SA medical distributions, and property tax receipts.
- Document Charitable Contributions Contemporaneously: Retain bank records, credit card receipts, or written acknowledgment letters from recipient charities. The IRS requires formal written acknowledgment for any single contribution of $250 or more.
- Log Business and Medical Mileage: Track business vehicle mileage using a dedicated mileage logging application, applying the IRS statutory standard rate (72.5 cents per business mile for 2026).
- Compare Standard vs. Itemized Totals: Sum your SALT payments, mortgage interest, and charitable donations. If the total exceeds $16,100 (single) or $32,200 (joint), itemize on Schedule A.
Frequently Asked Questions About Common Tax Deductions
What is the difference between a tax deduction and a tax credit?
A tax deduction reduces your taxable income, lowering the amount of earnings subject to taxation based on your marginal tax rate. A tax credit provides a direct, dollar-for-dollar reduction of your actual calculated tax liability.
Can I claim these deductions if I take the standard deduction?
Certain deductions, known as above-the-line deductions on Form 1040 Schedule 1, can be claimed even if you take the standard deduction. These include contributions to health savings accounts, traditional IRAs, educator expenses, and student loan interest. Deductions for state and local taxes require itemizing on Schedule A.
How much student loan interest can I deduct?
Eligible borrowers can deduct up to $2,500 of qualified student loan interest paid during the year. The deduction is subject to statutory income limitations and phases out across specified Modified Adjusted Gross Income thresholds.
What is the maximum I can contribute to an HSA?
For the 2026 tax year, the maximum statutory contribution to a Health Savings Account is $4,400 for self-only coverage and $8,750 for family coverage. Account holders age 55 and older can make an additional $1,000 catch-up contribution.
What qualifies as a deductible charitable donation?
Taxpayers can deduct cash contributions and documented non-cash donations of goods made to qualified 501(c)(3) charitable organizations. Claiming charitable write-offs generally requires itemizing deductions on Schedule A, although non-itemizers can claim a limited above-the-line deduction.
This article is for educational purposes only and should not be considered personalized tax advice. Consider consulting with a certified public accountant (CPA) or enrolled agent (EA) for guidance specific to your financial situation.
For educational purposes. Consider your own circumstances before making financial decisions. Read our editorial policy.
From reading to planning
Explore the numbers for yourself.
Use our free calculators to compare scenarios and understand your options.